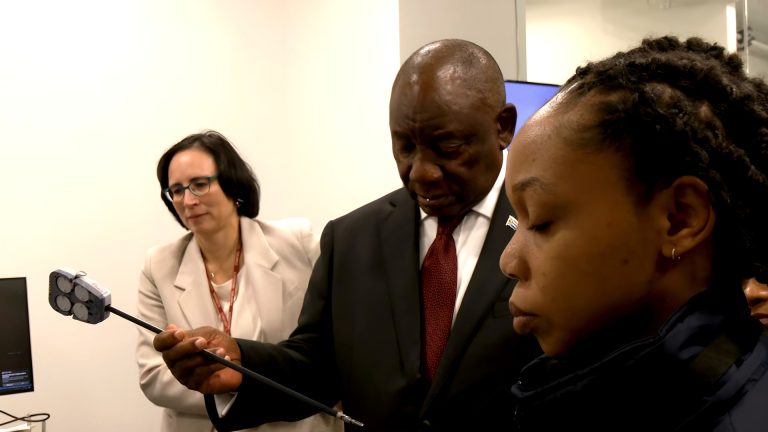


Bank and fintech executives at AFIS in Luanda said currency shortages, fragmented regulation and thin banking networks keep intra-African payments slow, even as PAPSS expands.

LUANDA – A payment between Lagos and Accra can still be routed through correspondent banks in London or New York before it lands, executives told a dinner on the sidelines of the Africa Financial Industry Summit, illustrating how far Africa’s financial plumbing lags its free trade ambitions.
“If I have to pay someone in Ghana from Lagos, the transaction has to move to the UK or the US before it lands in Ghana,” said Lasbery Oludimu, Yellow Card’s vice-president for global operations and managing director in Nigeria, according to The Africa Report. “It’s the currency. It’s the regulators and the regulation. It’s the rails.”
Lekan Adelekan, executive director for business development at FirstBank UK, pointed to a further constraint: too few African banks have the balance sheets and reach to provide trade finance and risk management across several jurisdictions. He said banks with regional networks should also act as an “intelligence partner”, helping clients find suppliers and investors in neighbouring markets.
Yellow Card offers infrastructure for businesses to move value across borders using digital tokens, including dollar-pegged stablecoins, which can settle around the clock. But the technology does not remove foreign exchange shortages or regulatory constraints, and businesses still need to convert local currency in and out.
Within the conventional system, the Afreximbank-backed Pan-African Payment and Settlement System (PAPSS) lets participating banks settle cross-border payments in local currencies. PAPSS chief executive Mike Ogbalu said in September that the platform operates in more than 30 countries and connects 24 national and regional central banks, more than 200 commercial banks and payment providers, and 16 switches.
“Banks, as you said, are regulated; we have the balance sheet and the risk assessment capacity. But fintechs have the reach, and the nimbleness to move at a speed banks can’t,” Adelekan said. Oludimu agreed, adding: “We can’t scale without regulation.”
The African Continental Free Trade Area aims to remove barriers to trade, but cheaper tariffs mean little if settling an invoice across a border is slow and expensive. For companies trading within Africa, including Botswana exporters selling into SADC and beyond, local-currency settlement and wider PAPSS participation could reduce dependence on scarce dollars. The executives’ message was that payments alone will not be enough: firms also need longer-term credit, which they said pension funds, insurers and development lenders must help provide.

Written by
Tumisang Bogwasi, Founder & CEO of Brimco. 2X Award-Winning Entrepreneur. It all started with a popsicle stand.