

Morgan Stanley reports that Hong Kong's office sector is positioned for a sharper recovery than New York, driven by supply constraints and shifts in global capital flows.
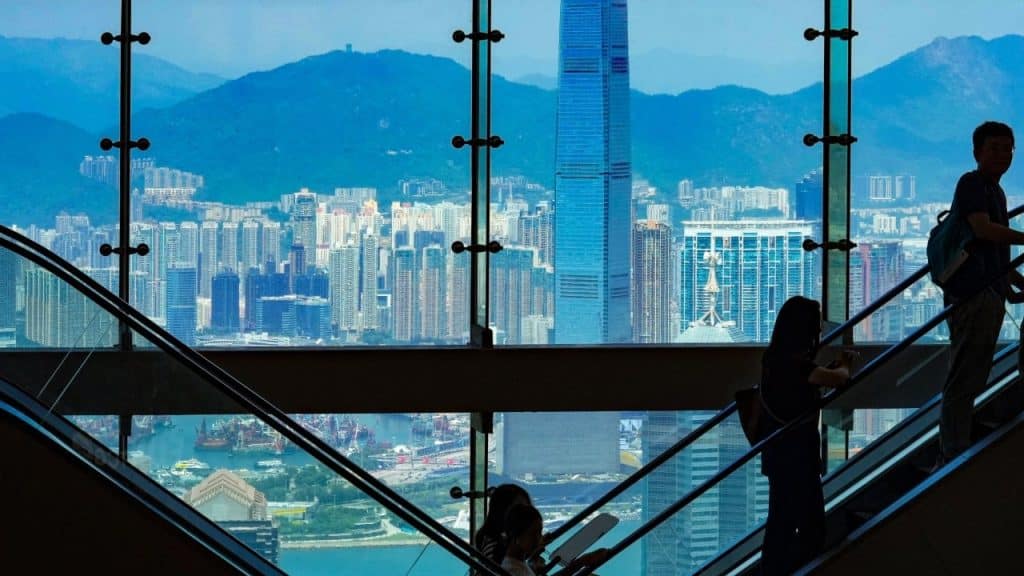
HONG KONG, China, Morgan Stanley projects that the Hong Kong office market holds more significant upside potential than its New York counterpart over the next 12 months. While both global financial hubs have faced headwinds from sustained high interest rates, the Asian market’s structural dynamics suggest a more pronounced recovery path than its North American peers.
The investment bank noted that Hong Kong is currently benefiting from a lack of new supply, which is expected to support rental floors. In contrast, the New York office market continues to grapple with a surplus of inventory and a fundamental shift in work patterns that has kept vacancy rates elevated.

The divergence between the two markets stems from the timing of their respective property cycles. In Hong Kong, the pipeline for new Grade A office completions has slowed, creating a vacuum in demand for premium assets. This scarcity is likely to allow landlords to regain pricing power as the global macroeconomic environment begins to stabilize.
Conversely, the New York commercial real estate landscape remains burdened by the ‘flight to quality’ trend. While premium tenants are seeking modern, energy-efficient spaces, older towers in central districts are struggling to maintain occupancy and valuation levels. Morgan Stanley suggests that New York requires a more significant catalyst to match the recovery trajectory currently seen in the Asian market.
Financial analysts also highlight the role of the Hong Kong Monetary Authority and its peg-linked monetary policy. As the PBOC explores potential shifts from the Federal Reserve, the cost of borrowing in Hong Kong may eventually ease, providing further liquidity to commercial investors. This shift could act as a catalyst for the renminbi-denominated transactions that dominate the local commercial sector.
The recovery of the Hong Kong office market is a critical bellwether for broader sentiment toward Asian commercial real estate. As capital flows seek higher yields outside of Western markets, the stabilization of Hong Kong rents could trigger a resurgence in institutional investment across Singapore and Shanghai.
Furthermore, the stability of the yuan-linked dollar is closely tied to the health of these urban financial centers. If Hong Kong achieves the projected upside, it may bolster the city’s role as the primary gateway for international capital entering the Chinese mainland economy.

Written by
Tumisang Bogwasi, Founder & CEO of Brimco. 2X Award-Winning Entrepreneur. It all started with a popsicle stand.